Short Term Business Loan
Cash flow can't wait? Borrow £5,000 to £25 million unsecured, or up to £100 million with security, over terms of 3 to 24 months, with decisions in as little as 24 hours. Rates from 4.5% APR. Prospera Finance compares short-term business loans from lenders across the UK and charges no fees, so you can check what you could borrow with no obligation.
Prospera Finance is a credit broker, not a lender.
YOUR ESTIMATE
Illustrative estimate only. Your quote depends on your circumstances.
Access to the entire UK market
High street banks, challenger banks and specialist lenders, compared for you with one application.
No broker fees
We are paid by the lender on completion. You pay us nothing, and there are no hidden costs.
No credit searches by Prospera Finance
You get indicative terms with no credit searches and no effect on your credit score. Lenders carry out their own searches later, and a hard search only ever happens with warning.
Here's some of the lenders we work with
The basics
What is a short term business loan?
A short term business loan is a commercial loan repaid over 3 to 24 months, designed for immediate needs: a tax bill due next month, stock for the Christmas rush, a cash flow gap while you wait on invoices. Unlike a 5-year bank loan, it's built for speed: streamlined applications, open-banking-based underwriting, and funding in days rather than weeks.
It's working capital finance, not investment capital. You borrow a lump sum, use it for the business, and repay in fixed instalments: daily, weekly, or monthly depending on the lender. Because this is short term funding, lenders focus on your recent trading performance and cash flow to service the loan.
What can you use it for?
VAT and tax bill funding
HMRC doesn't negotiate. A 3-month business loan bridges the gap between the bill landing and the cash arriving.
Stock and inventory funding
Buy the Christmas stock in October, sell it in December, repay in January: a 6-month business loan matched to the season.
Cash flow loans
Payroll is Friday; your biggest customer pays in 30 days. A short-term cash flow loan keeps the lights on without drama.
Equipment finance
A replacement van, new machinery, upgraded IT: spread a 12-month business loan over the asset's first productive year.
Growth opportunities
Take a bulk-buy discount, fund a new contract that needs upfront spend, or hire ahead of demand.
At a glance
Short term business loan: the key facts
| Amounts | £5,000 to £25 million unsecured; up to £100 million with security (full ranges in the amounts table below) |
|---|---|
| Terms | Typically anywhere from 3 to 24 months |
| Repayments | Daily, weekly, or monthly: fixed schedule agreed upfront |
| Security | Unsecured (usually with a director's personal guarantee) or secured against assets |
| Pricing | Interest charged as APR; always compare on APR and total amount repayable (see below) |
The wider business-loan ranges we arrange are in the amounts table below.
Eligibility
Could your business qualify?
- UK-registered business: limited company, LLP, or partnership (sole traders: see FAQ)
- 6+ months trading: most lenders want to see some track record; a few consider newer businesses
- Business bank account: 6 - 12 months business bank statements or open banking are required
- Affordable repayments: the lender will stress-test your cash flow, not just your turnover
- Adverse credit considered: a less-than-perfect credit history doesn't automatically disqualify you, though rates will reflect the risk; some lenders specialise in funding businesses that the high street banks have turned down
How much can you borrow?
Unsecured short-term loans run from £5,000 to £25 million. For larger amounts, secured business loans can reach £100,000,000 depending on the security offered. The right amount is always the one your cash flow can repay comfortably, and we'll sanity-check that with you before anything is submitted.
| Unsecured business loans | From £5,000 up to £25,000,000, no assets required. |
|---|---|
| Secured business loans | Borrow up to £100,000,000, using property or other assets as security. |
| Start-up loans | Access up to £250,000 through government-backed schemes. |
Secured loan terms can run anywhere from 1 month to 30 years. This page focuses on the short-term end of that range.
Check what you could borrow: no credit search to enquire, no obligation.
Check what you could borrowMore ways we can help
The wider toolkit: other business finance we arrange
A short-term loan is one option. Where a different product fits your situation better, we arrange that instead. Tap any of the following to read more.
Secured business loans
Unsecured business loans
Working capital loans
Asset finance
Business loans with poor credit
Start-up loans
Invoice finance
Bridging finance
Business overdraft facilities
The honest view
Advantages and disadvantages of short term business loans
Advantages
- Fast decisions and funding: decisions in as little as 24 hours, with funding in days, not the weeks or months of a traditional bank loan.
- No collateral on unsecured loans: borrow £5,000 to £25 million without a charge over your premises, stock, or equipment.
- Short commitment: the debt is cleared within 3 to 24 months with no early repayment fees, so you save on interest compared to a longer term loan.
- Flexible use: tax bills, stock, payroll gaps, equipment, or a growth opportunity: the funds are not tied to one asset.
- Builds your credit profile: repaying on time strengthens the business credit file for future borrowing.
Disadvantages
- Higher cost than long-term borrowing: short terms and fast underwriting mean higher APRs than a 5-year loan. Typically 6% to 18% APR for well-qualified borrowers, and more for weaker profiles.
- Personal guarantee usually required: unsecured borrowing normally means the directors personally guarantee the loan, putting personal assets at risk if the business cannot pay.
- Tight repayment schedules: repayments over a short term are larger, and daily or weekly schedules can strain cash flow if trade dips.
- Late payment can hurt your credit: missed payments can damage both your business and your personal credit files.
Costs, honestly
What does a short term business loan cost?
Short-term business funding is more expensive than long-term borrowing: you're paying for speed and flexibility. Here's how to read any quote without getting burned.
How lenders price: the APR
Take a £10,000 loan over 12 months at an annual interest rate of 6%. The monthly repayment is £860.66, the total interest is £327.97, and the total amount repayable is £10,327.97. Add a 1% lender arrangement fee (£100) and the total cost of credit rises to £428.97, which pushes the representative APR to 8.18%, above the 6% headline rate. That's exactly why you should always ask for the APR: it's the only number that lets you compare two offers honestly.
Representative example
Borrow £10,000 over 12 months at an annual interest rate of 6%, with a lender arrangement fee of 1% (£100). Monthly repayment: £860.66. Total amount repayable: £10,327.97. Total interest: £327.97. Total cost including fee: £428.97. Representative 8.18% APR.
Other costs to check
Arrangement fees (sometimes 1 to 3%) and late-payment fees. Early repayment: many short-term lenders let you settle early and only pay interest for the time you actually borrowed, but minimum terms (often 1 to 3 months) can apply, so we'll confirm the early-settlement position on any quote before you commit. We'll flag every one of these upfront.
Risk warning: Late repayment can cause you serious financial problems. Missed payments may damage your business and personal credit files, trigger additional fees, and, where a personal guarantee was given, put your personal assets at risk. Never borrow more than the business can comfortably repay.
Ready to check what you could borrow?
No broker fees, and no credit search by us when you enquire.
Read this first
Risks and important considerations
Shorter-term loans mean higher repayments
Spreading £25,000 over 12 months is over £2,000 a month before fees. Only borrow what your cash flow can repay in a bad month, not just a good one.
A personal guarantee puts your personal assets at risk
Most unsecured loans require directors to guarantee the debt personally. If the business defaults, your personal assets, including your home, can be pursued.
Secured borrowing puts your assets at risk
A secured loan is cheaper because the lender can sell the asset used as collateral (property, vehicles, equipment) if the business cannot repay the loan.
Late repayments can compound fast
Missed payments can trigger late fees, and a lender can demand the full balance early or act on any security or personal guarantee.
Daily and weekly repayments drain accounts quickly
They suit businesses with steady daily takings; but they can strangle cash flow for businesses paid monthly by only a few big customers.
More loans can introduce more risk
The more loans a business has, the more commitments it has to pay them. Highly leveraged businesses may find it difficult to meet their financial obligations.
Your credit file
Credit searches, explained honestly
We underwrite your deal in-house and provide indicative terms with no searches and no commitment. Later in the process, lenders will run a soft credit search, which does not affect your credit score. A small number of lenders run a hard search, which can affect your score, and we will always let you know beforehand. Because we only send you to the most competitive lenders for your situation, searches stay to a minimum.
The process
How to apply in 3 steps
Tell us what you need
The amount, what it's for, and when you need it by. 60 seconds is all it takes, no lengthy forms, and no credit search by us.
We compare the whole market and present your options
Only one application; and we compare lenders across the whole UK market and present your options side by side with a breakdown of APR and total amount repayable, so you know exactly what you're paying. Decisions in as little as 24 hours.
Funds released
Funds can be released within 1 to 3 business days, and in some cases, same-day funding is possible.
Estimate your cost
Business loan calculator
Move the sliders to see what a short-term business loan could cost. The estimate includes the effective APR, because that is the figure that lets you compare offers honestly.
Your estimate
This calculator gives an estimate only, not a quote or an offer. Your actual rate depends on your business and the lender. For larger or secured borrowing, figures are quoted case by case: call us on 020 8050 6446.
Case study
A real refinance result
One client came to us as they were paying 18% on an existing loan. We refinanced it with a £150,000 unsecured business loan from a high street bank, over 6 years at 8.5%, cutting the interest rate by more than half and improving their cash flow position significantly. Longer terms like this are available where the case suits them; this page focuses on the short-term end of business lending.
Broker vs going direct
Why use a broker instead of going direct to a lender?
| Going direct to a lender | Using Prospera Finance (broker) | |
|---|---|---|
| Lenders compared | One | Full market access: high-street banks, challenger banks and specialist lenders |
| Speed | Their pipeline, their timeline | Matched to the fastest suitable lender for your case |
| Rate | Their rate card | Compared side-by-side with APR and total repayable |
| Structure | Their standard product | 3 to 24 month terms |
| Declined? | Start over | Re-matched the same day |
| Fee | £0 (but no comparison) | £0 in almost all cases; any rare direct fee is communicated upfront at the assessment stage |
| Credit searches | A search with every application | We run no searches ourselves; lenders soft search first, and we warn you before any hard search |
Going direct means one lender's appetite, one rate card, and, if they decline you, a hard search on your file for nothing. We compare the market on APR and total cost. Because we run no credit searches ourselves, your credit file stays untouched until a lender needs to search, and we will warn you before any hard search. As a short-term business finance broker, we also reach specialist lenders you won't find on comparison sites.
Client reviews
What our clients say
Prospera Finance is rated on Google by UK business owners.
"Hafez has been an absolute pleasure to work with. He takes the time to explain the options available, which is so important, especially for my client base who are not used to having business debt."
"Very pleased with my options from Prospera Funding. The best thing is that this company is open on weekends, both Saturday and Sunday, which is the only time I have to go through admin and paperwork."
"I was very happy to meet Hafez and his team at Prospera Funding. From the start, they were professional, responsive, and highly knowledgeable about the funding options available to support our business growth."
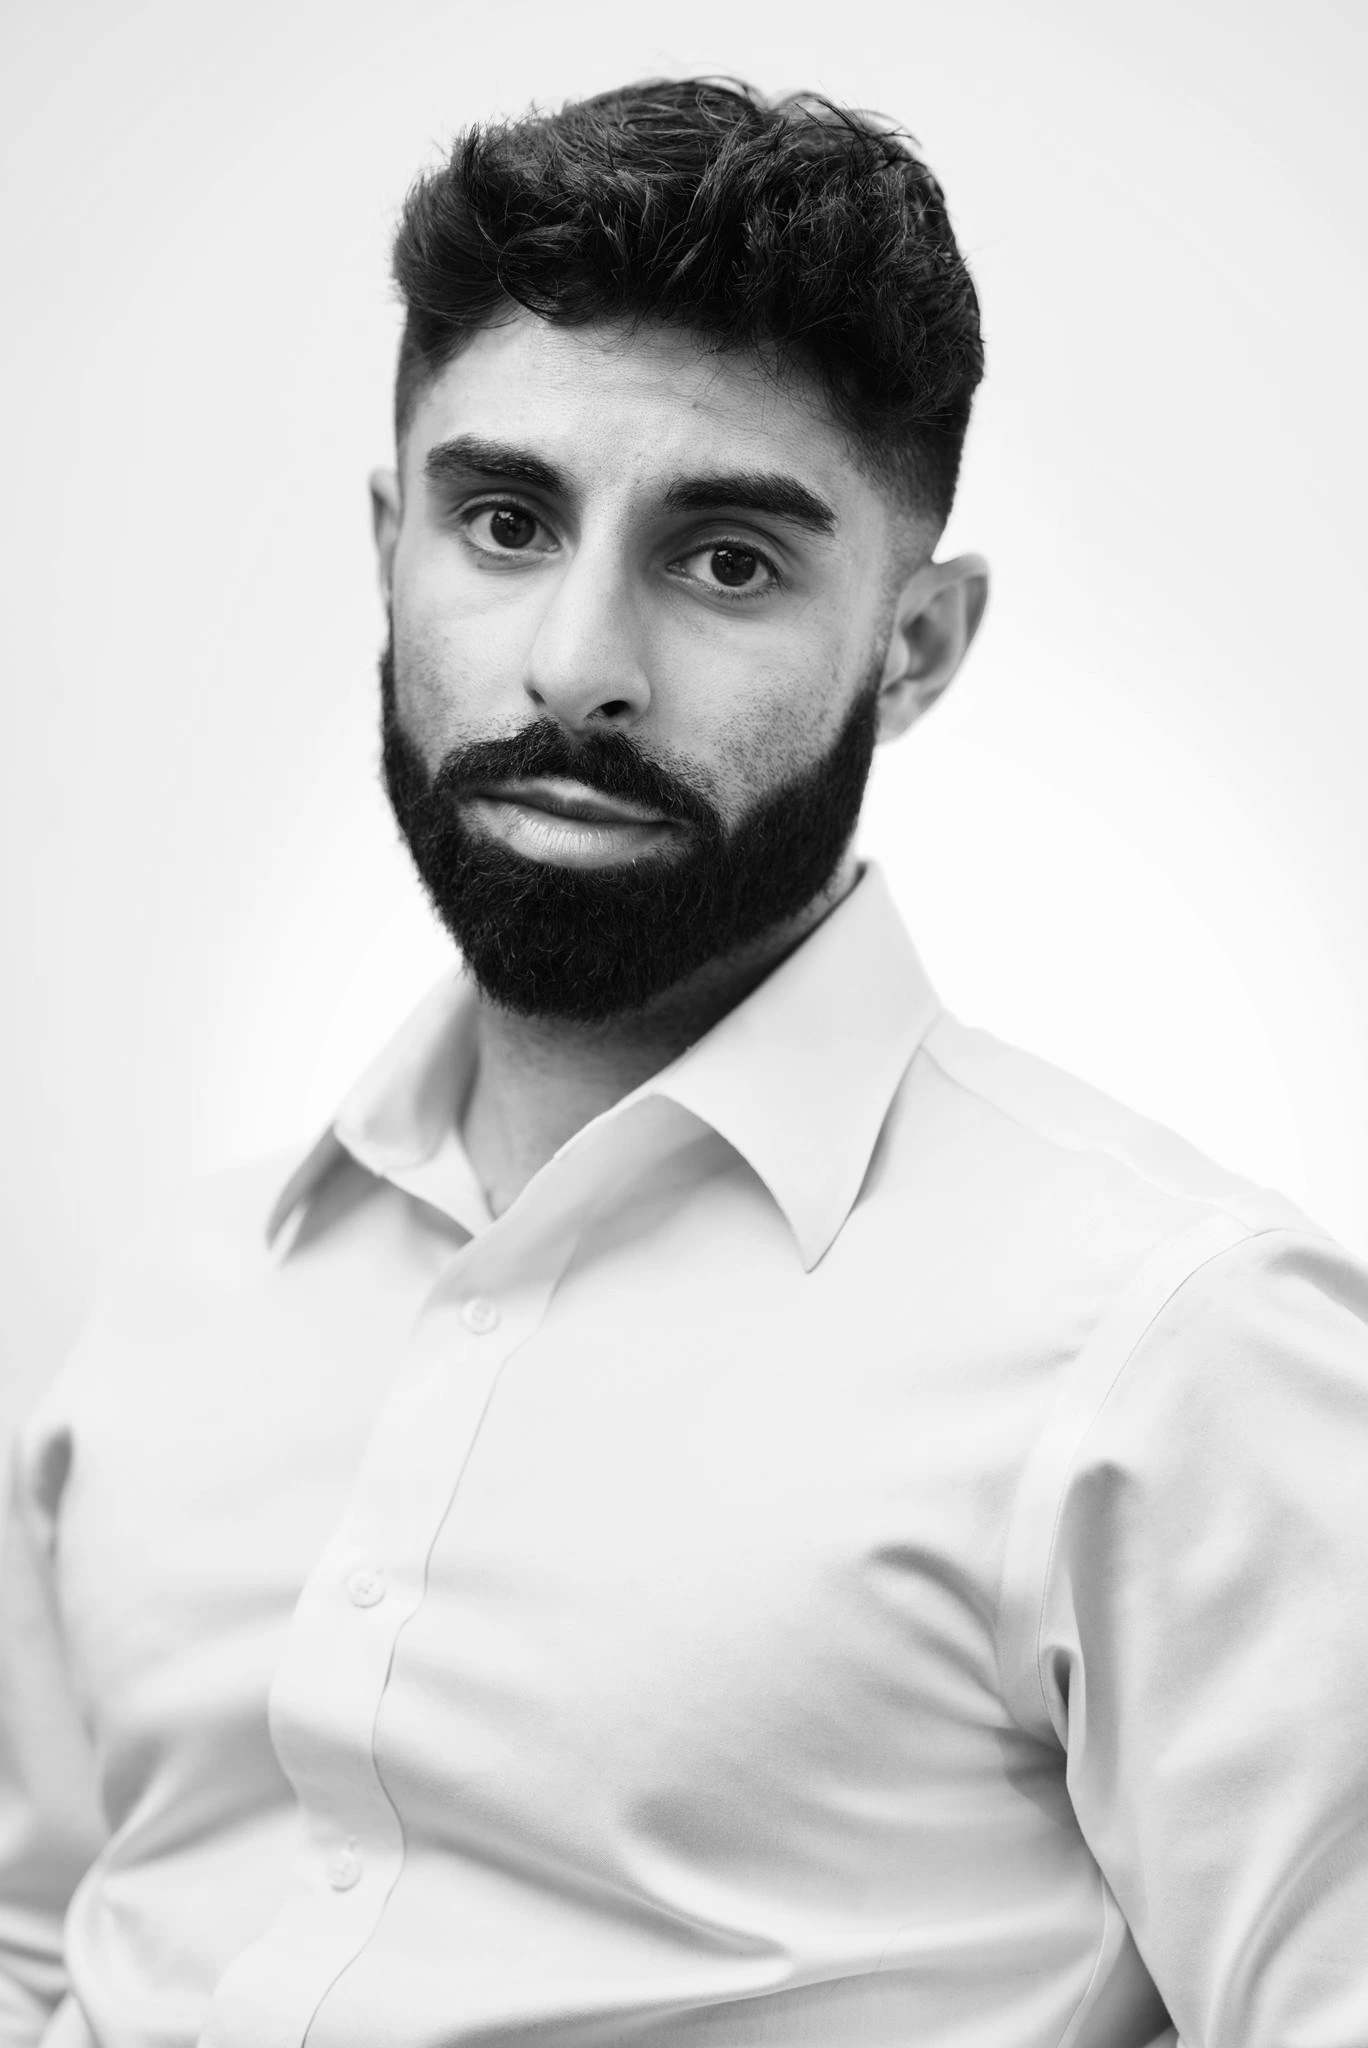
Expert reviewed
Reviewed by Hafez Feili
Hafez Feili is the senior finance broker behind Prospera Finance, the trading name of Prospera Funding Limited. Prospera Finance serves clients across the UK, arranging commercial business and property finance through access to the entire UK market of lenders: high street banks, challenger banks and specialist lenders. Prospera Finance also offers a range of consulting services to serve the needs of UK business owners.
Risk warning: Late repayment can cause you serious financial problems. Think carefully before borrowing. Your business credit file, and where a personal guarantee is given your personal assets, may be at risk if you do not keep up repayments.
Last reviewed: October 2026. Finance figures on this page are reviewed quarterly.
Questions, answered
Frequently asked questions
How do short term business loans work in the UK?
Who qualifies for a short term business loan?
Can I get a short term business loan with bad credit?
How fast can I get funding?
Do I need collateral for a short term business loan?
Are personal guarantees mandatory for company loans?
Are short term business loans expensive?
Can sole traders apply for short term business finance?
Keep exploring
Related finance options
Quick Bridging Finance
Short-term secured finance for property deals.
Explore bridging loans →Invoice Factoring for Small Business
Release cash tied up in unpaid invoices.
Explore invoice finance →Commercial Finance Broker London
Longer-term commercial property finance.
Explore commercial mortgages →Alternatives to business loans
| Type of finance | How it works |
|---|---|
| Revolving credit facility | Gain ongoing access to funds as needed; interest is charged only on what you withdraw. |
| Invoice finance | Unlock cash quickly by borrowing against outstanding customer invoices. |
| Asset-based lending | Finance business-critical equipment or vehicles through manageable monthly payments. |
| Bank overdrafts | Cover temporary cash shortfalls directly through your business bank account. |
| Equity funding | Secure capital by offering a stake in your business to external investors. |
Need funding this week, not next quarter?
No credit search to enquire, no obligation. Tell us what you need and we will compare the whole market for you.
Or email enquiries@prosperafinance.co.uk. Open Mon to Sat 09:00 to 18:00, Sun 09:00 to 14:30.